USDA rural development
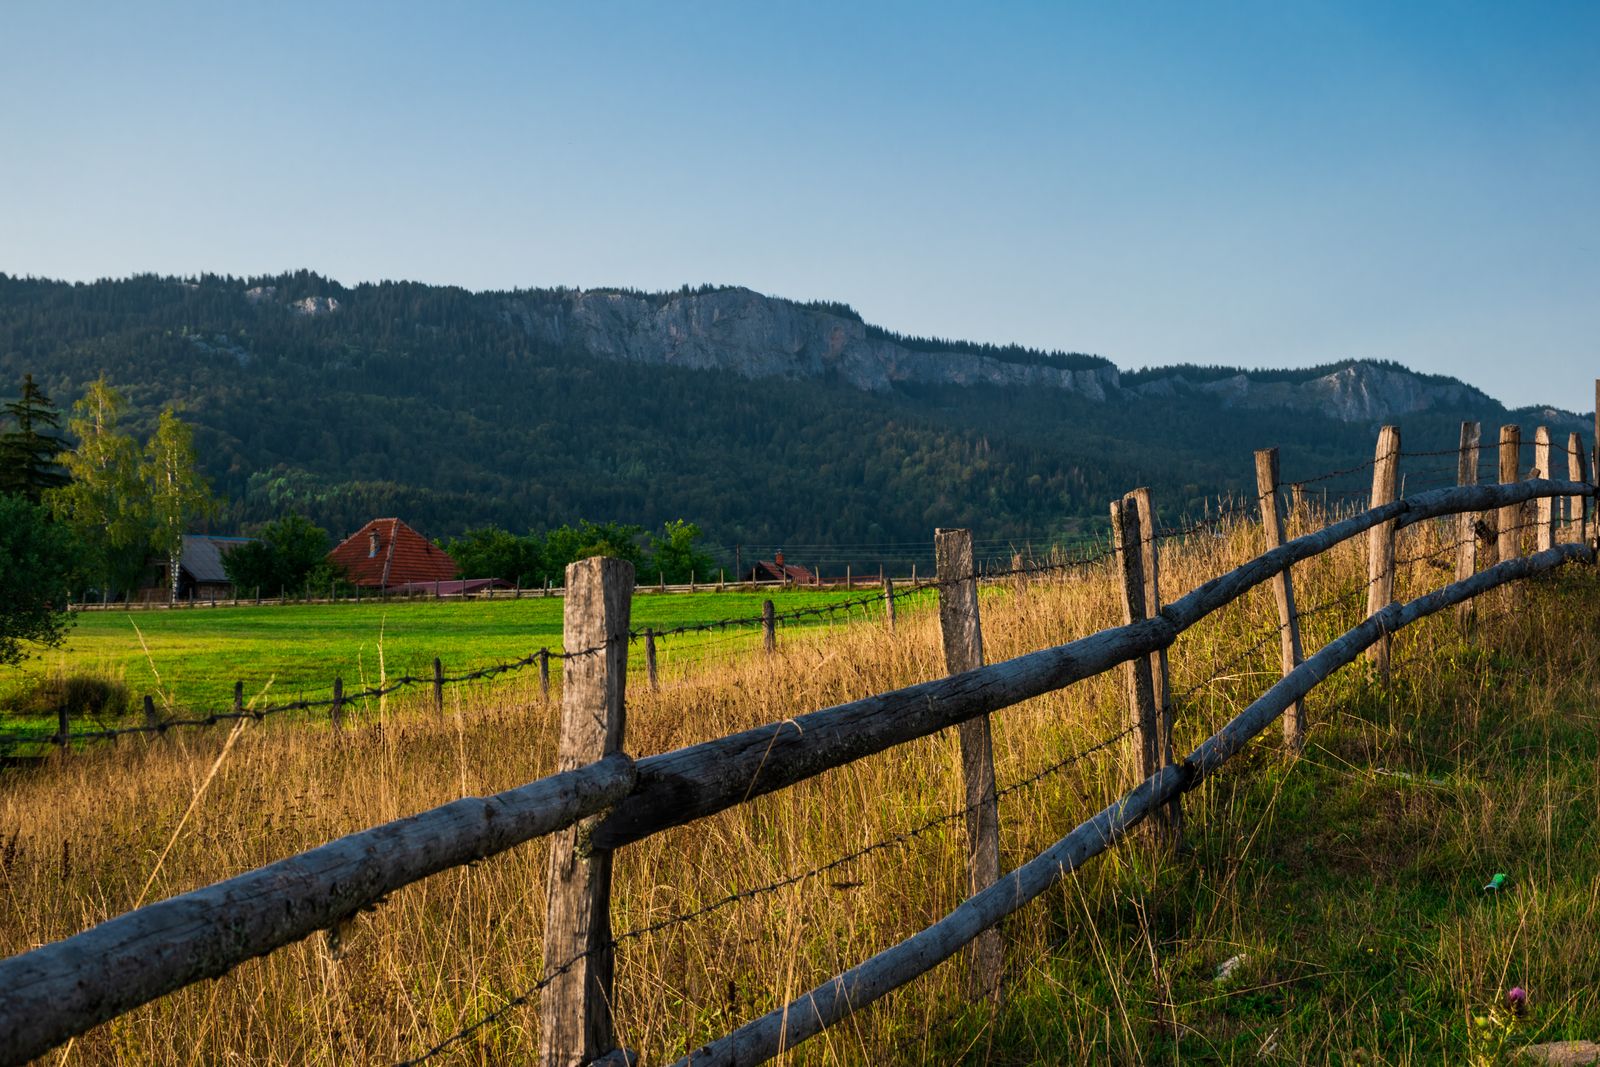
The most overlooked zero-down loan in New Mexico. Large parts of Valencia County, eastern Sandoval County and the communities along the Rio Grande corridor sit inside eligible tracts, and buyers assume they do not qualify because the word 'rural' sounds like a farm.
- Down payment
- 0% in eligible tracts
- Income test
- Household income limit, counts all adults
- Guarantee fee
- Upfront fee plus a smaller annual fee
What this program actually is
USDA Guaranteed Rural Housing has two eligibility tests, and both are unusual. The property has to sit in an eligible area, which we check by address before you fall in love with a house. The household has to sit under an income limit, and the income test counts every adult in the household, not only the borrowers, which surprises people with an adult child living at home.
In exchange you get no down payment, a guarantee fee structure that is materially cheaper than FHA mortgage insurance, and the ability to finance closing costs into the loan when the appraised value comes in above the contract price.
Turn times are the real trade-off: the file goes to the lender and then to the state USDA office for a commitment. We build that into the contract timeline rather than discovering it in week four.
- Down payment
- 0% in eligible tracts
- Income test
- Household income limit, counts all adults
- Guarantee fee
- Upfront fee plus a smaller annual fee
- Property type
- Owner-occupied single family, no income-producing acreage
- Extra step
- State USDA commitment after lender approval
What you get from us on this program
- Address-by-address eligibility check before you write an offer
- Household income worksheet including non-borrower adults and childcare deductions
- Timeline built around the state commitment step so your contract dates are realistic
- Comparison against FHA and conventional 3% down on the same property
- Guidance on financing closing costs when the appraisal supports it
How the file runs
- 01
Map and income check
We confirm both tests in the first conversation, not after you are under contract.
- 02
Full credit package
Documents are collected to USDA standard from day one.
- 03
Lender approval
Underwritten by one of the two panel lenders that run USDA desks in-house.
- 04
State commitment
We submit and track the conditional commitment with the state office.
- 05
Close
Final walkthrough, closing disclosure review, keys.
What moves your pricing on this program
These are the inputs an underwriter and a rate sheet actually react to. Nothing on this page is a quote.
| Factor | Why it matters |
|---|---|
| Property location | Eligibility is tract by tract, not town by town |
| Household income | Limits vary by county and household size |
| Existing home ownership | Generally must not own an adequate dwelling |
| Property use | Working acreage and outbuildings can disqualify |
| Turn time | Add roughly a week for the state commitment step |
All rates, APRs, payments, fees and timelines referenced on this site are sample figures for illustration only. They are not an offer of credit and not a commitment to lend. Equal Housing Opportunity.
Often compared with
USDA rural development questions
Not covered here? Call (505) 555-0135 or send us a note. Se habla español.
Parts of the far north and west edges have historically been eligible while the core is not. We check the exact address, because the boundary runs through neighborhoods.
For the household income eligibility test, yes, income from adult household members is generally included even when they are not on the loan.
Land value has to be reasonable relative to the home, and income-producing acreage is not allowed. Small acreage with a home on it is often fine.