The statement date, not the due date, is what your credit score reads
The most common credit mistake we see costs buyers an entire pricing tier, and it is fixed by paying a card ten days earlier.
Rafael Garza, The Garza Mortgage Team
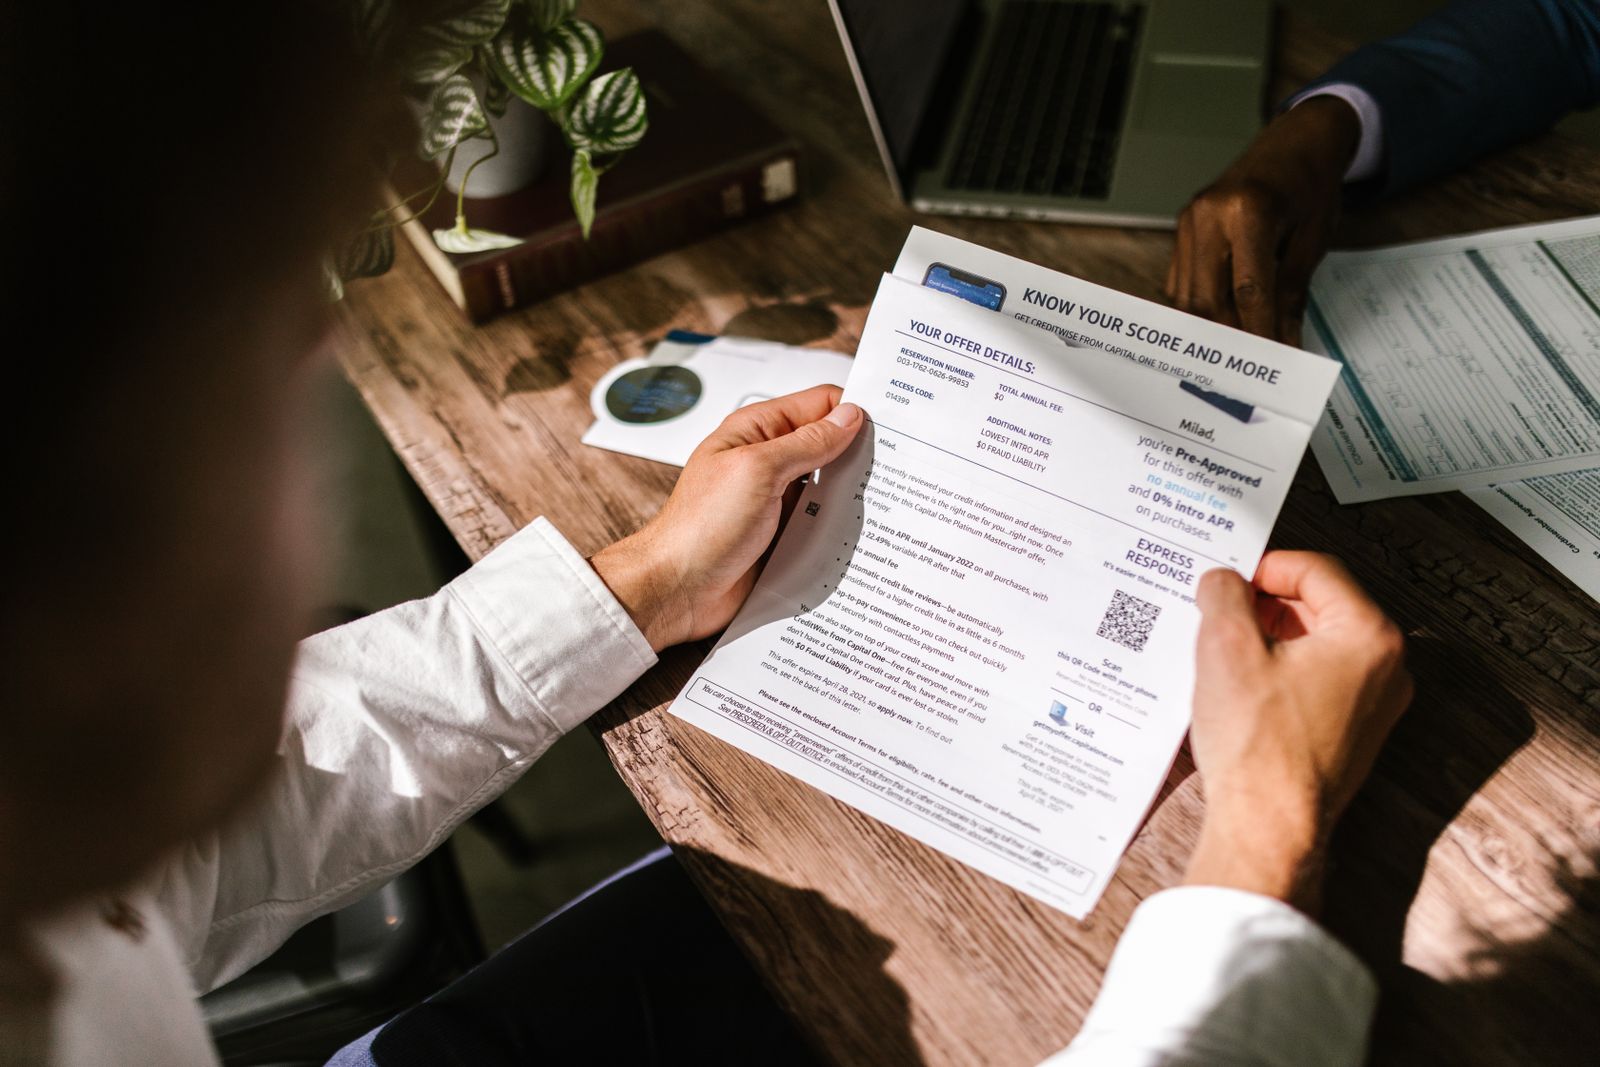
A buyer at a Saturday workshop told me she pays her credit cards in full every month and had never missed a payment, so her utilization must be zero. Her mid-FICO was 673. She could not understand it.
Her card had a statement date on the 3rd and a due date on the 28th. She paid in full on the 26th, every month, faithfully. But the balance that gets reported to the bureaus is the balance on the statement date, which in her case was a card sitting at 81% of its limit. As far as every scoring model was concerned, she was carrying that balance permanently.
How utilization is actually scored
Amounts owed makes up roughly 30% of a FICO score, and revolving utilization is the bulk of it. It is calculated two ways at once: per card, and across all your cards together. Both matter, which is why consolidating three cards onto one is usually a bad idea before a mortgage even though the total debt has not changed.
- Under 30% on each individual card is the first target
- Under 10% across all cards is the second, if you can reach it
- Zero on every card is very slightly worse than a small balance on one, because the model likes to see active use
- A card that is closed keeps its payment history for a while but removes its limit from the calculation immediately
The fix takes one phone call and one calendar entry
Call each card issuer and ask for the statement closing date. Not the due date. Then set a reminder for three days before it and make your payment then. The balance that reports will be the one you want the bureaus to see, and you have not spent a dollar more.
Moving from 75% to under 30% utilization commonly moves a mid-FICO by 20 to 40 points. That is often a full pricing tier.
Why a pricing tier is worth real money
Conventional pricing steps at 660, 680, 700, 720 and 740. Crossing one of those breaks is typically worth something in the region of an eighth to a quarter of a point in rate, and on a loan with mortgage insurance it also moves the monthly insurance factor, which can be the larger of the two effects (sample figures).
For the buyer at the workshop, the difference between a 673 and a 703 was not academic. It changed her monthly mortgage insurance and her rate adjustment at the same time. She paid two cards down before the statement dates, we ordered a rapid rescore, and she came back three weeks later at 708.
What a rapid rescore does and does not do
A rapid rescore asks the bureaus to update a specific, documented change ahead of the normal reporting cycle. It works for a paid-down balance, a corrected balance or a removed error. It requires a letter from the creditor and it has to be ordered by the lender, so it is not something you can do yourself.
It does not manufacture points. If nothing genuine has changed, nothing happens. And once it is running, do not charge anything, because a new balance landing mid-rescore is a frustratingly common way to waste the exercise.
Three months is usually enough
If you are twelve weeks out from applying, you have time to do this properly. Dispute genuine errors first because those take 30 days, stop opening anything new, then work the statement dates. Our credit readiness timeline sets out the whole sequence week by week.
All figures in this article are sample figures for illustration only.
Want this applied to your file?
Send documents in the morning and you will have real numbers from several wholesale lenders the same afternoon. No credit pull until you say go.
Keep reading
You were not declined by the rules. You were declined by an overlay.
The guideline said yes. The lender's own extra condition said no. Here is how to tell the difference, and why it matters more than the rate.
7 min read
Reading a builder's lender incentive without the sales pressure
New construction in Rio Rancho comes with a closing cost credit if you use the builder's lender. Sometimes that is the best deal on the table. Here is how to tell.
6 min read
What makes a pre-approval letter strong enough to win an offer
Most pre-approval letters are a paragraph with a number in it. Listing agents know the difference, and so should you.
6 min read